The Complete Home Buying Guide for First-Time Buyers

The Complete Home Buying Guide for First-Time Buyers
---
meta_title: "Home Buying Guide for First-Time Buyers"
meta_description: "Learn the complete home buying process for first-time buyers. Financial prep, professional guidance, and actionable steps to homeownership."
---
Buying a home follows a step-by-step process that begins with financial preparation and ends at closing. First-time buyers benefit from self-education, planning, and professional guidance from real estate agents, mortgage brokers, and insurance agents. A clear roadmap reduces stress and keeps the journey manageable.
Key Takeaways
- Financial preparation and assembling a professional support team prevent lost negotiating power and unexpected delays.
- A realistic price range comes from subtracting all non-housing expenses from total monthly take-home pay.
- Mortgage pre-approval signals financial qualification and seriousness, strengthening offers in competitive markets.
- A home inspection identifies structural defects, outdated electrical systems, and hidden water damage before purchase.
What are the first steps in buying a home?
The first steps in buying a home center on financial preparation and assembling a professional support team. Buyers who skip these foundational tasks often lose negotiating power and face unexpected delays. A home buying guide always starts with numbers, not neighborhoods.
How do buyers determine a realistic price range?
A realistic price range emerges from a clear comparison of monthly income against all non-housing expenses. Buyers add up total monthly take-home pay and subtract recurring debts, living costs, and savings goals. The remaining figure sets a firm ceiling for a mortgage payment. This real estate fundamentals exercise prevents emotional overspending.
Why should buyers work with professionals early?
Experienced professionals catch costly mistakes before they happen. Real estate agents, mortgage brokers, and insurance agents each bring specialized knowledge to the property purchase process. Their guidance helps buyers navigate loan options and market conditions that first-timers rarely see coming.
The financial readiness phase follows a logical sequence:
- Audit personal finances. Review credit reports, verify income documentation, and calculate total monthly debt obligations.
- Set a firm budget. Determine the maximum affordable monthly payment using the income-minus-expenses method.
- Research loan types. Compare conventional, FHA, and other mortgage products to match the buyer's financial profile.
- Engage a mortgage broker. Secure pre-approval to strengthen any offer before touring properties.
First-time homebuyer tips always emphasize pre-approval over casual browsing. A buyer who tours homes without financing clarity loses leverage in competitive markets. Market fundamentals shift constantly, but a locked-in budget keeps the search grounded. The home inspection checklist comes later; right now, the priority is knowing exactly what the bank will lend.
How do I get pre-approved for a mortgage?
Mortgage pre-approval signals to sellers that a buyer is financially qualified and serious. A lender reviews income, assets, and credit to issue a conditional commitment for a specific loan amount. Without this document, offers carry less weight in competitive situations.
What documents do lenders require for pre-approval?
Lenders typically request pay stubs, W-2 forms, bank statements, and tax returns from the past two years. Self-employed buyers face additional scrutiny and often submit profit-and-loss statements. Gathering these records before applying speeds the process considerably.
How does debt-to-income ratio affect pre-approval?
The real estate fundamentals of lending hinge on the debt-to-income ratio. This calculation divides monthly debt obligations by gross monthly income. Lenders use the result to cap the maximum mortgage payment a borrower qualifies for. A lower ratio opens access to better rates and higher loan amounts.
Follow these steps to secure pre-approval:
- Check credit reports from all three bureaus and dispute any errors.
- Calculate the debt-to-income ratio to understand borrowing limits.
- Save for a down payment, as larger contributions reduce monthly costs.
- Contact multiple lenders to compare rates and fee structures.
- Submit a uniform application with verified income and asset documentation.
A realistic budget anchors the entire property purchase process. Buyers should determine what monthly payment fits comfortably within their take-home income before shopping. Lenders may approve a higher amount than a household wants to carry. Sticking to a predetermined number prevents financial strain after closing.
What should I look for during a home inspection?
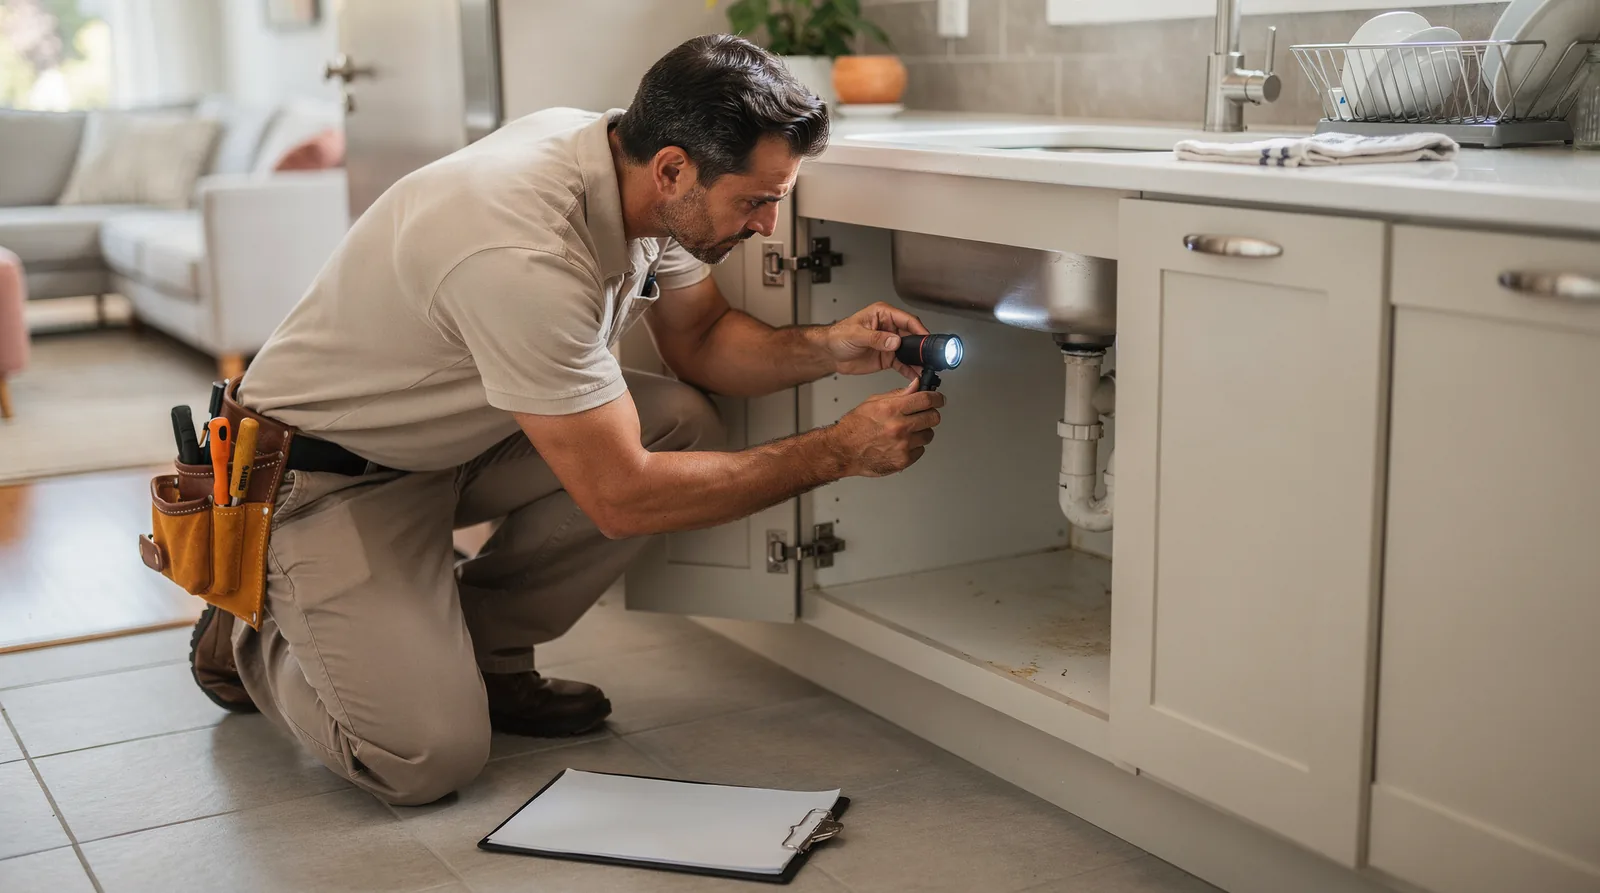
A home inspection checklist identifies potential issues before committing to a purchase. Buyers who skip this step risk inheriting costly structural defects, outdated electrical systems, or hidden water damage. The property purchase process hinges on evaluating the home's condition, systems, and structure thoroughly. A trained inspector examines the foundation, roof, plumbing, HVAC, and electrical panels. Buyers should attend the inspection in person. Observing the inspector's findings firsthand provides context that a written report alone cannot deliver.
What does a home inspector check?
The inspector assesses visible and accessible components. Foundations get checked for cracks or settling. Roofs are examined for missing shingles, leaks, and remaining lifespan. Plumbing systems undergo pressure tests and leak inspections. Electrical panels are reviewed for outdated wiring or safety hazards. HVAC units are tested for proper operation and age. Attics and crawl spaces reveal insulation quality and ventilation issues. Every major system falls under scrutiny.
How do I use the inspection report?
A real estate agent helps buyers interpret inspection reports and negotiate repairs. Travelers notes that working with experienced professionals such as real estate agents guides buyers through these decisions. The report becomes a negotiation tool. Buyers request credits or repairs for significant defects. Minor cosmetic issues rarely warrant concessions. Market fundamentals like local property values influence what buyers should expect from an inspection. In competitive markets, sellers resist extensive repair requests. Buyers prioritize safety hazards and functional failures over cosmetic preferences.
A standard home inspection checklist covers these areas:
- Foundation and structural integrity
- Roof condition and estimated age
- Electrical system safety and capacity
- Plumbing function and leak detection
- HVAC performance and maintenance history
- Attic insulation and ventilation
- Windows, doors, and exterior drainage
Buyers who understand real estate fundamentals approach inspections strategically. The goal is not a perfect home. The goal is an informed purchase decision backed by documented evidence of the property's true condition.
How do I make an offer and negotiate the price?
A buyer makes an offer by submitting a written purchase agreement that states the price, terms, and contingencies. The offer price reflects local market conditions and recent comparable home sales. Without a data-driven offer, a buyer risks overpaying by thousands of dollars or losing the property entirely to a better-prepared competitor.
Real estate fundamentals shape every negotiation. An experienced real estate agent helps craft a competitive offer based on current market fundamentals. Agents analyze comparable sales, days on market, and listing price trends. This analysis prevents emotional bidding that ignores actual property value.
What contingencies should a buyer include in the offer?
Contingencies protect the buyer from unexpected problems. Standard contingencies cover financing, the home inspection checklist, and the appraisal. A financing contingency allows the buyer to exit if the mortgage falls through. An inspection contingency permits renegotiation or withdrawal when major defects surface.
First-time homebuyer tips consistently warn against waiving the appraisal contingency. Skipping this protection leaves a buyer obligated to close even when the home appraises below the offer price. The gap between the loan amount and purchase price then falls entirely on the buyer.
How does the negotiation process work after submitting an offer?
The seller accepts, rejects, or counters the offer. A counteroffer changes the price, closing date, or contingencies. The buyer then responds with another counter or accepts the revised terms. This back-and-forth continues until both parties sign a final agreement.
The property purchase process rewards preparation. Buyers with mortgage pre-approval and flexible closing timelines hold stronger negotiating positions. Sellers view these buyers as lower-risk and more likely to close without delays. A complete home buying guide emphasizes that speed and certainty often matter more than offering the highest price.
What happens at closing and after I buy?
Closing finalizes the property purchase process with signed documents, paid costs, and transferred ownership. Buyers who skip preparation for this final stage risk delays that jeopardize locked-in interest rates and negotiated terms.
The closing meeting brings together buyers, sellers, agents, and a settlement officer. Documents are reviewed and signed. Funds change hands. Keys are delivered. Travelers notes that working with experienced professionals during this phase helps buyers navigate the final decisions confidently.
What documents do buyers sign at closing?
The stack includes the promissory note, deed of trust, and closing disclosure. Buyers verify loan terms, interest rates, and monthly payment amounts before signing. The closing disclosure deserves particular scrutiny. Federal rules require buyers receive this form three business days before closing, providing time to compare final costs against the initial loan estimate.
What costs continue after the purchase?
Ongoing expenses begin immediately. Property taxes, homeowners insurance, and maintenance costs replace the one-time closing payments. First Bank's homebuying guide emphasizes that budgeting for these recurring obligations prevents financial strain in the first year of ownership. Smart buyers set aside money for repairs and upkeep. Neglecting this budget leaves owners scrambling when the roof leaks or the furnace fails.
Real estate investment tips center on viewing the property as a long-term asset. Rocket Mortgage's 2026 homebuying guide frames homeownership as a wealth-building tool that appreciates over time. Market fundamentals shape decisions about future upgrades or eventual resale. Tracking local price trends, inventory levels, and interest rate movements helps buyers time improvements and future sales strategically. A home inspection checklist completed before closing identifies systems needing attention, but post-purchase monitoring of roof condition, HVAC performance, and foundation stability protects the investment year after year.
FAQ
What are the first steps in buying a home?
The first steps center on financial preparation and assembling a professional support team. Skipping these foundational tasks often causes lost negotiating power and unexpected delays.
### Why should buyers work with professionals early?
Real estate agents, mortgage brokers, and insurance agents bring specialized knowledge that helps buyers navigate loan options and market conditions.
Conclusion
Buying a home follows a clear sequence of steps, from financial preparation through closing and beyond. Each stage builds on the one before it, and skipping preparation weakens your position at the negotiating table. The process rewards buyers who understand market fundamentals, work with experienced professionals, and budget for ongoing costs after the keys change hands. Your next step is assembling your support team and getting pre-approved before you start looking at properties.
Categories
Recent Posts